FEMA Rules for NRI Property Buyers in India
NRIs can generally buy residential and commercial property in India. However, the FEMA rules for NRI property transactions restrict the purchase of agricultural land, plantation property, and farmhouses. They also regulate how an NRI pays for property and how eligible sale proceeds can later be sent abroad.
These rules apply across India. They operate alongside state property laws, registration requirements, tax rules and other checks that may apply to the specific property.
For an NRI planning a purchase, FEMA compliance should therefore be checked before transferring money or signing a binding transaction document. A legally permitted property purchase can still create problems if the property classification or payment route does not comply with the applicable rules.
What Are the FEMA Rules for NRI Property Transactions?
The FEMA rules for NRI property transactions govern how non-residents acquire, transfer and pay for immovable property in India. They also affect when property-related funds may be repatriated abroad.
FEMA stands for the Foreign Exchange Management Act, 1999. The current property framework includes the Foreign Exchange Management (Non-Debt Instruments) Rules, 2019, commonly called the NDI Rules.
Under Rule 24, an NRI or OCI may acquire immovable property in India other than agricultural land, a farmhouse or plantation property, subject to the prescribed conditions. Payment must come through permitted banking channels or eligible non-resident accounts.
In simple terms, FEMA answers three important questions:
- What type of property can an NRI acquire?
- How can the NRI legally pay for it?
- What happens when the property is transferred and money needs to move abroad?
These FEMA regulations for NRI transactions should not be confused with title or ownership verification. FEMA compliance does not prove that a seller has a clear title.
What Property Can an NRI Buy in India Under FEMA?
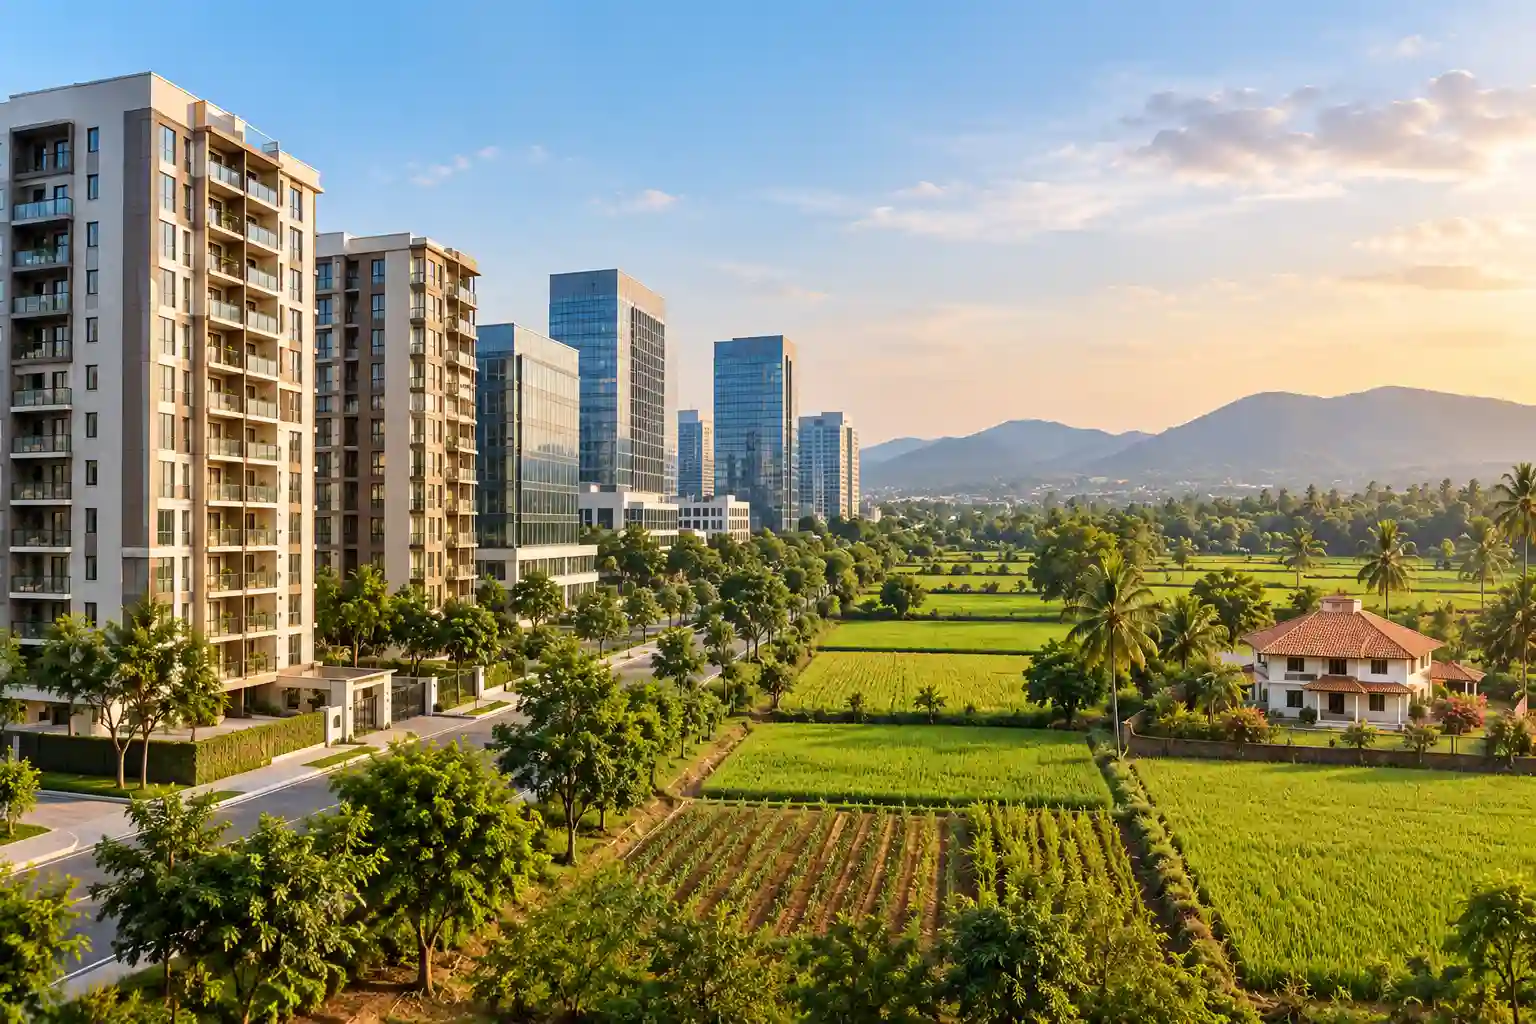
NRIs and OCIs can generally acquire residential and commercial immovable property in India without seeking prior RBI approval for an ordinary transaction that meets FEMA conditions.
This may include apartments, houses, residential plots and commercial premises, depending on the property’s legal classification. The key issue is not simply what the developer or seller calls the property. Its official land-use and revenue records should support that classification.
Before buying, NRIs should independently review the property documents required for legal verification. Title, encumbrances, approvals and seller authority remain important even where FEMA permits the acquisition.
What Property Cannot an NRI Purchase Under FEMA?
The FEMA guidelines for NRI property acquisition draw an important distinction between ordinary residential or commercial property and agricultural land, plantation property or a farmhouse.
An NRI or OCI cannot use the general permission under Rule 24 to directly purchase:
- Agricultural land
- Plantation property
- A farmhouse
Inheritance works differently. Rule 24 permits an NRI or OCI to inherit immovable property where the conditions specified in the rule are satisfied.
This distinction matters because agricultural land may look like an attractive residential investment but still remain agricultural in official records. A buyer should verify the legal classification rather than relying only on advertisements, layouts or future conversion promises.
FEMA Rules for NRI Property Purchase and Payment
The payment route is a core part of FEMA rules for NRI property purchase. A permitted property can still create a compliance issue if consideration moves through an impermissible method.
Rule 24 allows consideration to be paid using funds received in India through banking channels by inward remittance from abroad or funds held in a permitted non-resident account maintained according to FEMA.
The rules specifically do not permit payment for the transfer through foreign currency notes or traveller’s cheques.
Depending on the transaction, NRIs commonly use permitted banking arrangements involving NRE, NRO or FCNR(B) accounts. The Reserve Bank of India regulates these non-resident banking arrangements.
Maintain a clear banking trail for the transaction. Payment records may become important later when the property is sold and repatriation is requested.
Is RBI Approval Required for NRI Property Purchase?
An NRI or OCI generally does not need separate prior RBI approval to purchase ordinary residential or commercial property when the acquisition falls within Rule 24 and satisfies its conditions.
However, this does not mean every transaction involving a non-resident automatically qualifies. The buyer’s status, property type, payment method and proposed transfer structure can change the analysis.
Unusual transactions should be reviewed individually rather than assuming the general permission applies. The FEMA NRI guidelines also operate separately from state registration, stamp duty, RERA and tax requirements.
Can an NRI Sell Property and Repatriate the Money?
An NRI or OCI can transfer permitted immovable property, but sending the sale proceeds abroad is subject to FEMA conditions and the way the property was originally acquired and funded.
Rule 29 of the NDI Rules deals with repatriation of sale proceeds. For qualifying property, an authorised dealer bank may permit repatriation where the acquisition complied with foreign-exchange law and the original payment meets the prescribed conditions.
For residential property, Rule 29 also places a specific condition on repatriation of sale proceeds in relation to not more than two such properties.
Repatriation should therefore be planned before a sale rather than treated as an automatic final step. Tax compliance and bank documentation may also need separate attention.
Can an NRI Use a Power of Attorney for Property?
Yes. An NRI who cannot travel to India may use a properly executed Power of Attorney for permitted property-related acts, but the POA does not override FEMA restrictions.
A representative may assist with documentation, registration and other authorised steps depending on the wording of the instrument. However, giving someone a POA cannot make a prohibited property acquisition legal.
NRIs handling a transaction from overseas can read our detailed guide to NRI Power of Attorney for property in India.
FEMA Compliance Is Not the Same as Property Due Diligence
FEMA compliance tells an NRI whether the acquisition and movement of funds are permitted. It does not establish that the property has a clear title or all required approvals.
A buyer should separately verify the title chain, Encumbrance Certificate, land classification, approvals, litigation risks and the seller’s legal authority. Depending on the location and project, RERA and local land records may also matter.
For Bangalore transactions, our NRI property purchase in Bangalore guide explains these local checks in greater detail. Buyers can also understand the role of an Encumbrance Certificate in Karnataka when reviewing a Karnataka property.
Common FEMA Mistakes NRI Property Buyers Should Avoid
Most problems arise when buyers treat FEMA compliance as a formality instead of checking the transaction structure before money changes hands.
Common issues include:
- Assuming every plot advertised as residential is legally non-agricultural
- Using an incorrect payment route
- Failing to preserve inward-remittance and bank records
- Assuming a Power of Attorney removes FEMA restrictions
- Confusing inheritance rules with purchase rules
- Assuming FEMA compliance automatically confirms clear property title
- Planning repatriation only after the property has been sold
A careful review before payment is usually easier than trying to correct a compliance problem after registration.
Prashastha Legal Take
The most important point for an NRI buyer is to separate three questions: Can I legally acquire this property, does the seller have a valid and marketable title, and is my payment structure compliant?
FEMA mainly addresses the first and third questions. Property due diligence addresses the second.
For example, FEMA may permit an NRI to purchase a residential apartment, but that does not confirm the developer’s approvals or the seller’s title. Likewise, a clean title does not cure an impermissible FEMA payment structure.
NRIs purchasing property in Karnataka can consider a legal review through our property lawyers in Bangalore before making substantial payments or signing final documents.
Need Legal Help With an NRI Property Transaction?
NRI property transactions often involve FEMA compliance, title verification, banking documentation, Power of Attorney and local property laws at the same time.
Prashastha Legal assists NRI property buyers with legal due diligence, documentation and property-related legal requirements in Bangalore and Karnataka. Speak with the team before committing substantial funds when your transaction involves cross-border payment, remote execution or complex property records.
FAQs About FEMA Rules for NRI Property in India
These common questions explain the FEMA rules for NRI property transactions in simple terms. The exact position can depend on the property, residential status, source of funds and transaction structure.
1. Can an NRI buy property in India under FEMA?
Yes. An NRI can generally purchase residential and commercial immovable property in India subject to FEMA conditions. Agricultural land, plantation property and farmhouses do not fall under the general purchase permission.
2. Can an NRI buy agricultural land in India?
No. An NRI or OCI cannot directly purchase agricultural land under the general FEMA permission. Agricultural land may be acquired through inheritance where the conditions under the applicable rules are satisfied.
3. Does an NRI need RBI permission to buy a flat in India?
Usually, no. NRIs and OCIs generally do not need separate prior RBI approval to buy ordinary residential or commercial property when the transaction complies with the NDI Rules.
4. Can an NRI use an NRE or NRO account to buy property?
FEMA permits payment through funds received via banking channels or eligible non-resident accounts maintained under the applicable rules. The correct account and payment route should be checked for the specific transaction.
5. Can an NRI send property sale proceeds abroad?
Yes, in qualifying cases, but repatriation is subject to FEMA conditions. The property’s acquisition, original funding route, taxes and bank documentation can affect how the proceeds are remitted.
6. Can an NRI inherit agricultural land in India?
Yes. FEMA treats inheritance differently from a direct purchase. An NRI or OCI may inherit immovable property where the inheritance satisfies the conditions specified under the NDI Rules.
7. Can an NRI use Power of Attorney to buy property in India?
Yes, a properly executed Power of Attorney can allow an authorised person to perform specified property-related acts. However, a POA cannot bypass FEMA restrictions on property acquisition or payment.
8. Are FEMA rules different in Bangalore or Karnataka?
No. FEMA is a central law and applies across India. However, a property in Bangalore or elsewhere in Karnataka must also comply with relevant Karnataka property, land, stamp, registration and local approval requirements.